
Research
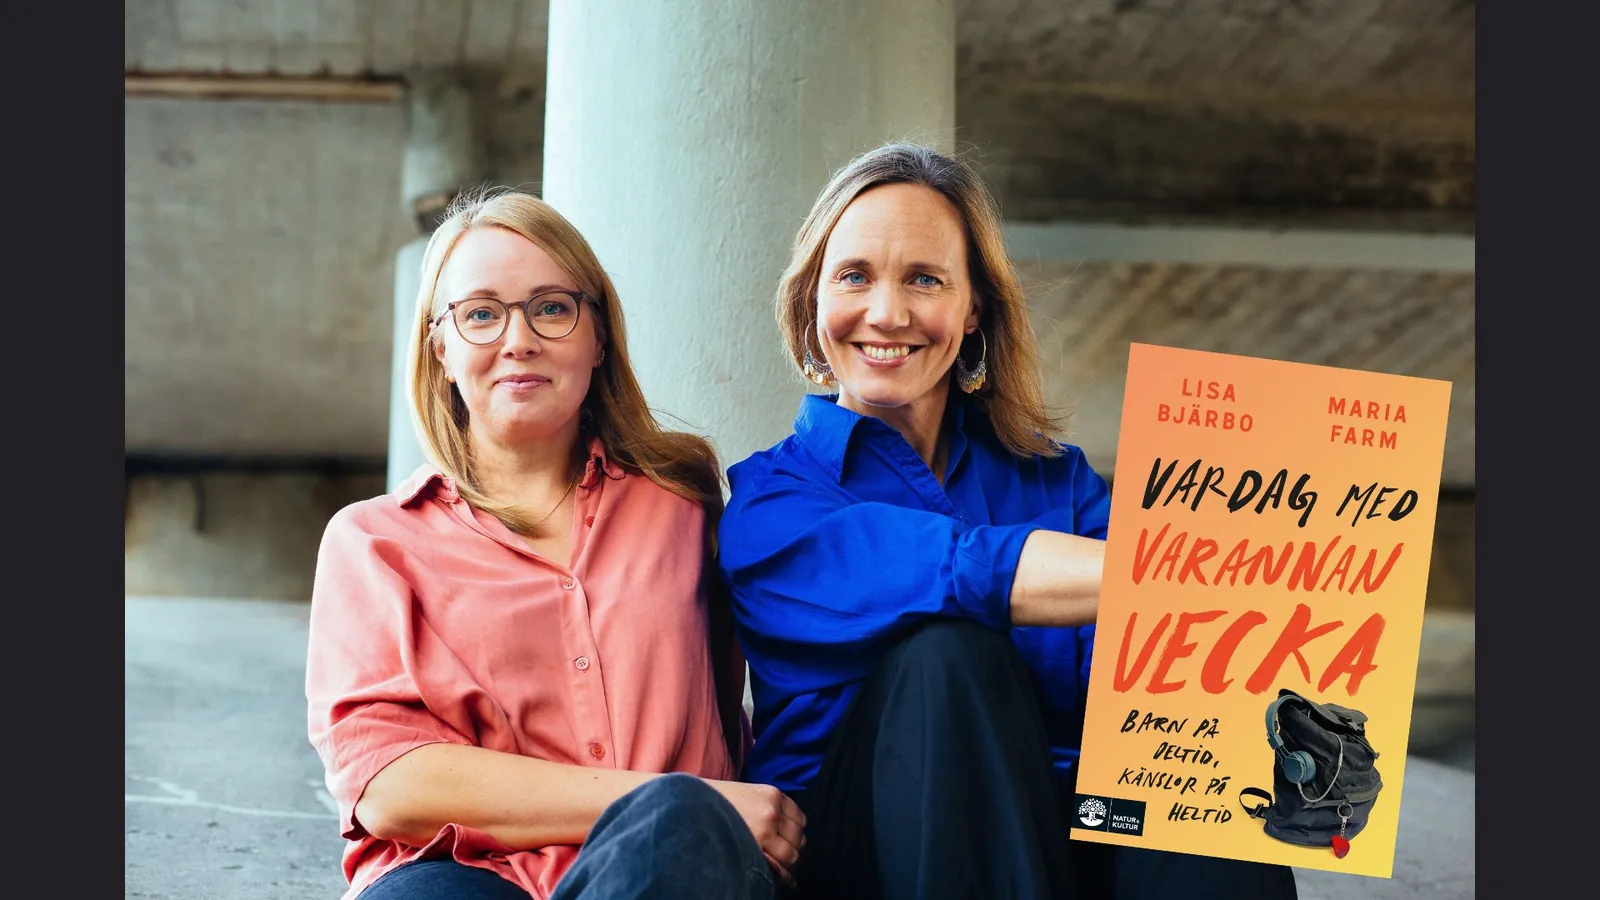
New Book: "Vardag med Varannan Vecka"
Psychologist Maria Farm and journalist Lisa Bjärbo wrote the book they missed about life in two homes — on money, equality and kids with special needs.
After a separation, one income suddenly has to carry a whole household. Magnus Hjelmér, everyday economist at ICA Banken, shares his best tips for protecting yourself if you lose your job or fall ill.
My first piece of advice is to join an unemployment insurance fund (a-kassa). It entitles you to a basic benefit if you lose your job — at most SEK 26,400 per month before tax (2023 level) for the first 100 days of compensation, after which the amount decreases. If you earn more than that, it may be time to arrange income insurance. It complements the a-kassa and can pay up to 80 percent of your salary for a number of months if you are laid off.
If you belong to a trade union, income insurance is usually included, but you can also take out a policy on your own if you are not a member. Income insurance usually has a qualifying period, so you need to have held it for a certain time before you become unemployed for it to apply.
Do you have income insurance? Then remember to update your registered salary every time it changes!
If your workplace has a collective agreement and you fall ill long-term, you are in most cases entitled to compensation equal to about 90 percent of your income. Since agreements differ, find out what applies to you — before you get sick. If you are not covered by a collective agreement, checking is even more important, so you don't risk being left with no compensation at all.
On the website Ersättningskollen you can calculate what your compensation would be.
If you want extra security, health insurance is an option. If you are ill long-term, it pays a monthly amount on top of the compensation you receive from Försäkringskassan (the Swedish Social Insurance Agency). Several parties offer health insurance: your employer, your union, or insurance companies directly. It is sometimes included in income insurance, so make sure you don't insure yourself twice.
Another way to secure your personal finances is to insure your borrowing costs. Loan protection is either linked directly to a loan or covers a fixed amount. In most cases it pays out in the event of involuntary unemployment or long-term illness. With mortgage protection, the insurance covers all or part of the loan payments. There is often a qualifying period for unemployment, usually between 150 and 180 days.
If your borrowing costs are large, unemployment or illness can quickly become a problem. It can be a real comfort to know you won't also be forced to move — that would only add pressure on you and your children. Just keep in mind that loan protection can be expensive month to month, especially when interest rates are high.
Buffer savings are invaluable when you face unexpected costs, such as sick leave or losing your job. Even if you have one or more of the protections mentioned here, it can take time before the money reaches your account — the buffer carries you through in the meantime. If you don't have a buffer yet, I recommend starting one right away. Read more about building a financial buffer at ICA Bank.
Magnus Hjelmér Everyday economist at ICA Bank
27 August 2026
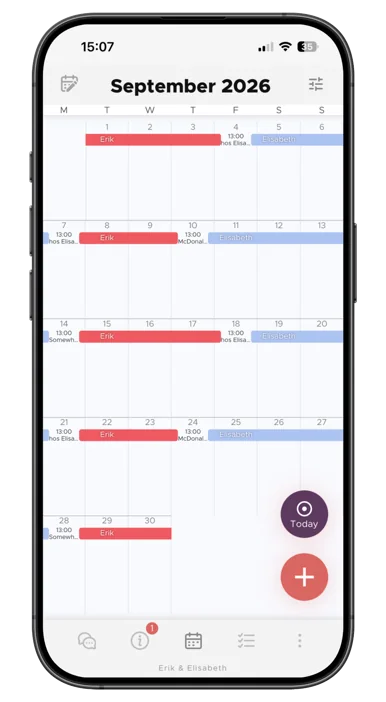
"The turning point came when we found the Every Other Week app. There's less fuss and both of us have a better handle on things. It feels so great!”
"Thank you so much for this app, it has finally gotten us to communicate!”
Research
Psychologist Maria Farm and journalist Lisa Bjärbo wrote the book they missed about life in two homes — on money, equality and kids with special needs.
For Children
Two homes can be a good thing for kids: more one-on-one time with each parent, more caring adults around, special traditions, and a calmer everyday life.
Research
Nowhere is alternate living as common as in Sweden. Child psychologist Malin Bergström on why everyday contact with both parents matters for children.